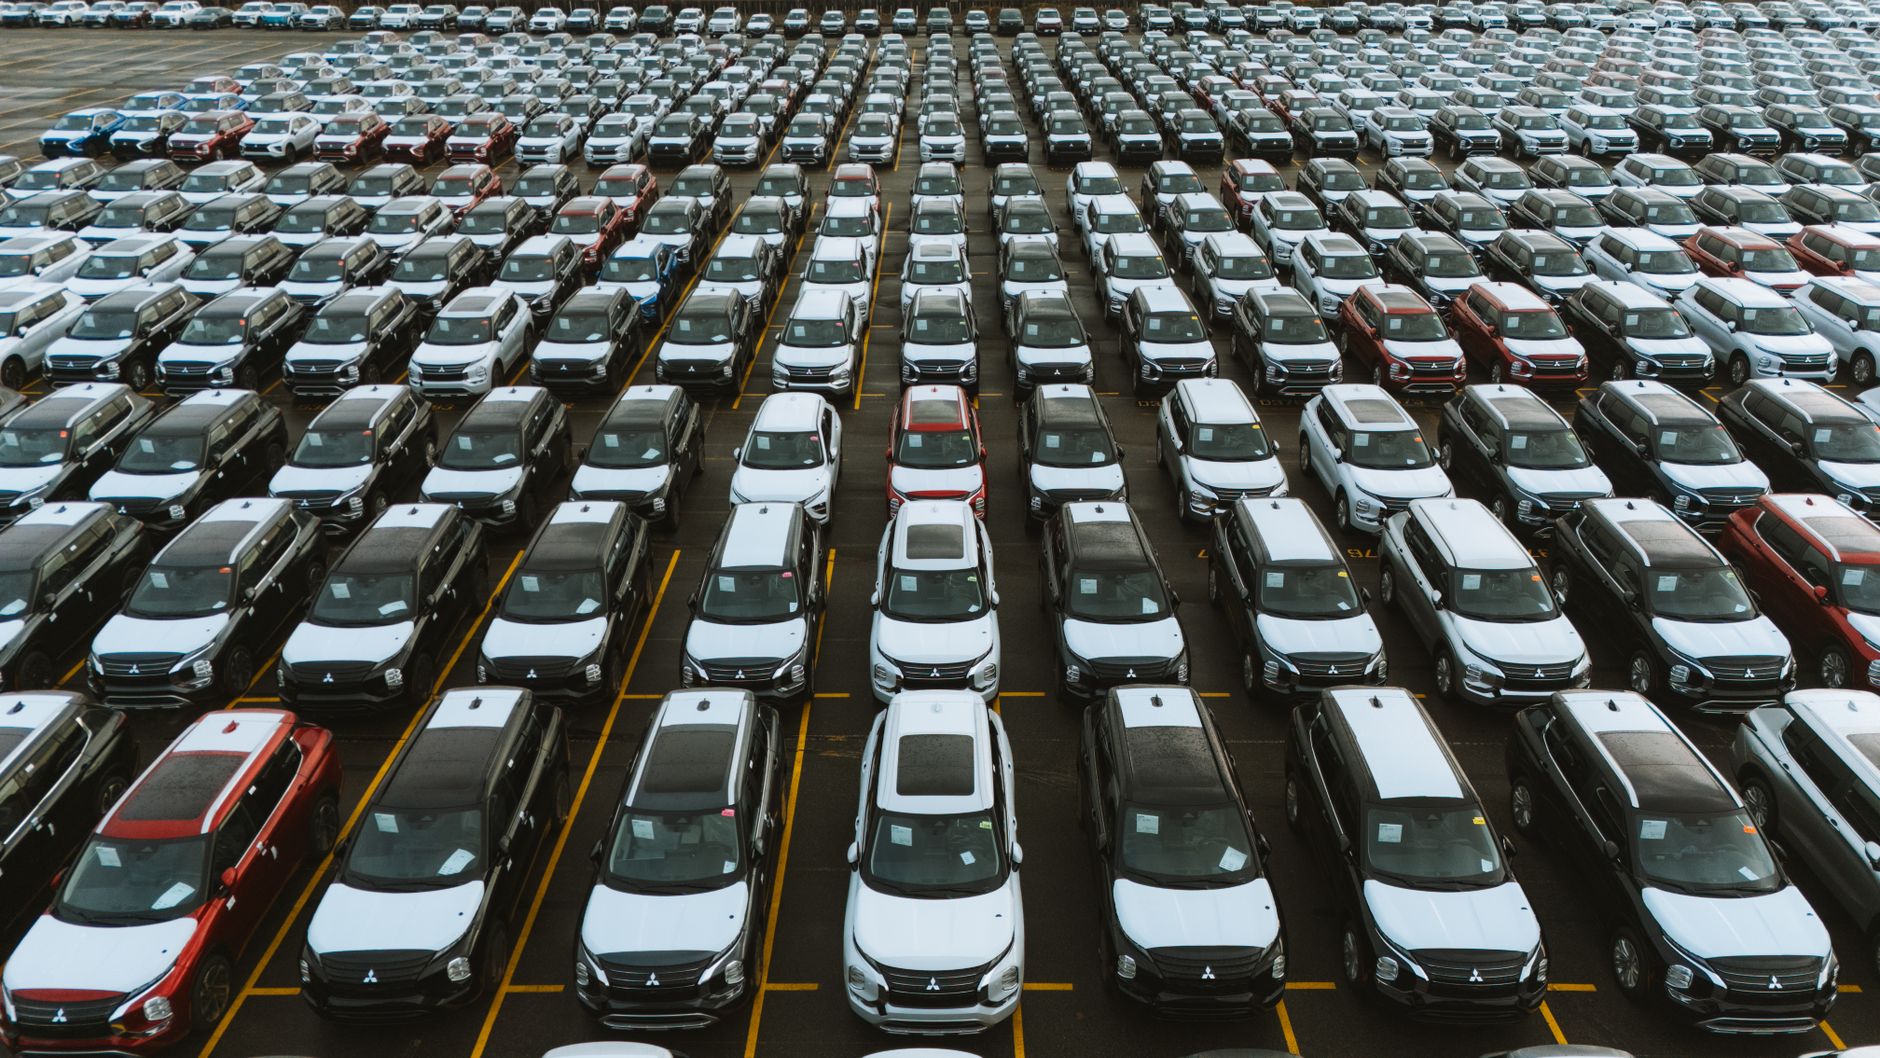
Carvana (NYSE: CVNA) delivered a quarter that looks like a triumph on its face. Retail units hit a record 217,385, up 39% year over year. Revenue surged 42% to $8.04 billion. Net income more than doubled to $483 million, and Adjusted EBITDA hit a record $800 million. The headline numbers are hard to argue with.
The market had priced in slightly more. EPS of $0.39 missed the $0.44 consensus estimate. Revenue cleared the $7.70 billion bar, yet the margin story proved more complicated than top-line growth suggests. Total GPU fell $365 year over year to $6,997; non-GAAP GPU dropped $410 to $7,093. Carvana attributed the compression to lower customer loan rates, lower wholesale GPU, and an estimated $200-per-unit drag from higher fuel prices and rising benchmark rates.
Here's where the quarter gets interesting. Carvana is deliberately giving back to customers through lower loan rates relative to benchmarks. This is a strategic choice to buy market share, not operational weakness. The trade-off is visible in the Adjusted EBITDA margin: 10.0%, still industry-leading, but down from 11.3% a year ago. The company grows fast and profitably. Each incremental dollar of revenue simply arrives at a lower margin than before.
Management's response amounts to a significant pivot. Beginning in 2027, Carvana will shift its primary reporting to GAAP metrics and target 3 million retail units at a 12.5% operating margin between 2030 and 2035. More consequential: after the Q4 2026 earnings call, the company will stop providing quarterly and annual financial outlooks. The rationale is that the business has entered a "long-term profitable growth phase" and that forward communication will focus on longer-term goals.
The move is defensible for a company that has proven its model scales. It also strips away a key transparency tool. Investors must now trust that management's internal compass is calibrated correctly, without the quarterly checkpoints that historically guided expectations. The reiterated FY2026 Adjusted EBITDA range of $2.7 billion to $3.0 billion, with an expectation of hitting the higher end, offers near-term comfort. The long-term 12.5% operating margin target implies a meaningful step-up from the current 8.9% GAAP operating margin.
Wholesale GPU deserves separate attention. Wholesale gross profit per retail unit fell 18.2% to $708, as retail units scaled faster than wholesale marketplace gross profit. This is structural. The wholesale business does not scale at the same rate as retail. As Carvana pushes toward 3 million units, the wholesale GPU drag will likely persist unless the company finds a way to monetize that channel more effectively.
On the balance sheet, Carvana ended with $3.05 billion in cash and $5.12 billion in committed liquidity resources. It deployed $53 million to redeem senior secured notes early, a modest debt reduction that signals confidence in cash generation. Operating cash flow for the first nine months was $900 million, up from $606 million a year ago, driven by higher net income and improved working capital management.
The forward read is mixed. Unit growth is undeniable. Market share gains in a flat industry are real. Yet GPU compression, the departure from quarterly guidance, and the long runway to 12.5% operating margins all suggest the easy wins are behind Carvana. The next phase hinges on whether the company can sustain growth while expanding margins, or whether scale eventually exacts its toll.
For now, the march continues. The terrain is getting steeper.