

Rocket Lab (NASDAQ: RKLB) just posted the kind of quarter growth-stage aerospace investors dream about. Revenue hit $268 million, topping the $257 million consensus by 4% and climbing 73% year-over-year. Backlog surged to $3.57 billion, a 52% jump from Q2. For the first time, the company turned positive on GAAP operating cash flow: $7.2 million.
The headline figures grab attention. The structural story lives in what's booked and how the balance sheet's transformed.
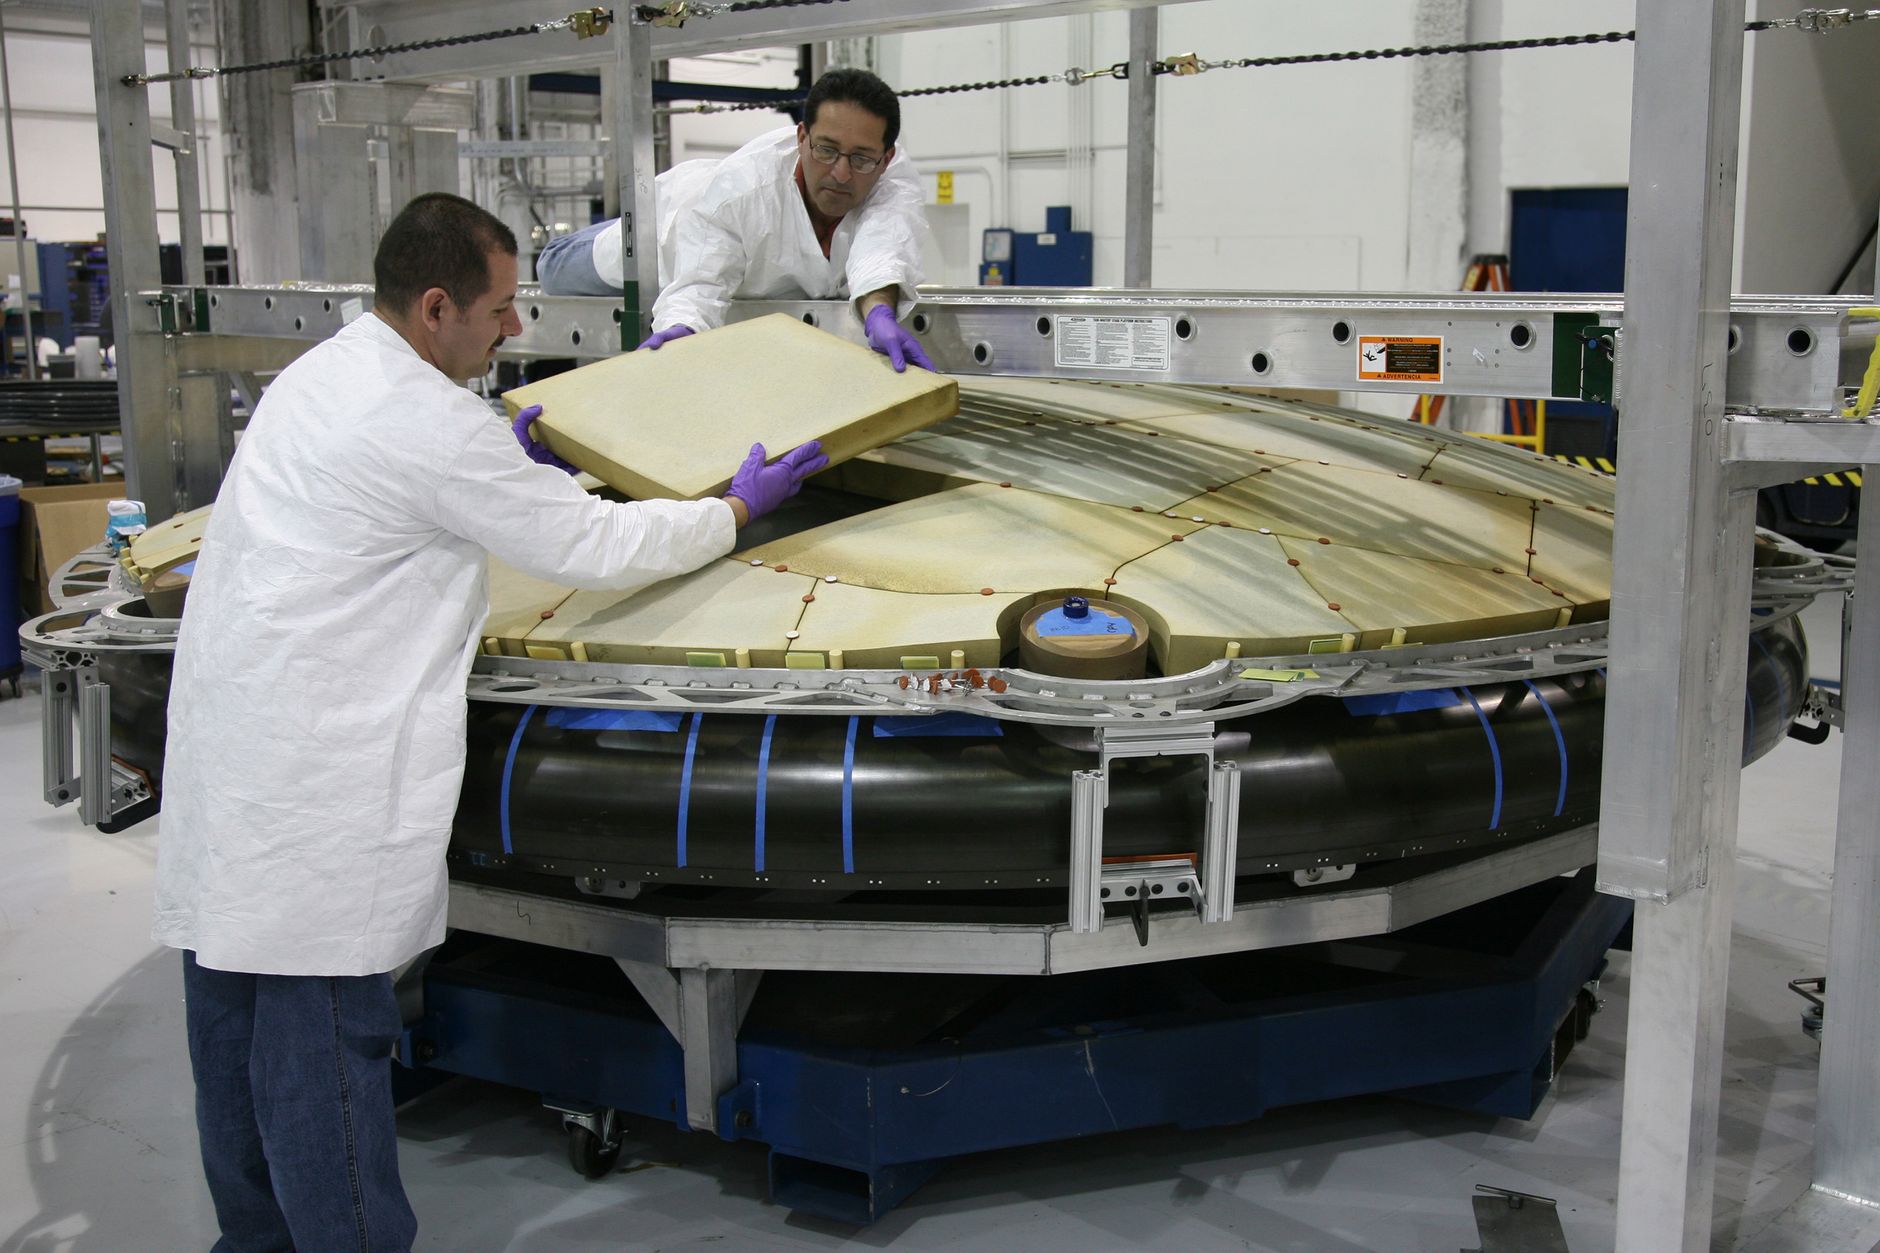
Nearly $1 billion of fresh backlog came from launch contracts signed in Q3 alone. Over $515 million of that is Neutron business from constellation operators, pushing the medium-lift rocket's manifest to 16 missions before its maiden flight. Rocket Lab also lifted Neutron's base launch price to $70 million, pointing to tightening industry capacity. First launch is now targeted for no earlier than 2027, though hardware milestones keep advancing at Launch Complex 3. Customers are paying premium rates for assured access on an unflown rocket. That says everything about supply-demand in the medium-lift market.
Both segments fueled the revenue beat. Product revenue hit $197.5 million, up 90% from $104 million a year prior. Service revenue rose 38% to $70.3 million. Gross profit landed at $90.1 million, producing a GAAP gross margin of 33.6% versus 37.0% in the year-ago quarter. The compression warrants attention. Non-GAAP gross margin of 38.4% also slipped from 41.9% in Q3 2025. Management pins this on mix: product revenue carries lower margins than services. Q4 guidance calls for GAAP gross margins of 34% to 36% and non-GAAP of 39% to 41%, suggesting sequential recovery. Hit the midpoint, and Q3 marks the bottom.
Operating expenses remain the anchor. GAAP operating expenses of $169.3 million exceeded gross profit by $79.2 million, yielding an operating loss of $79.2 million. R&D spending of $98.4 million continues to absorb Neutron development costs. On a non-GAAP basis, operating expenses were $130.2 million, narrowing the operating loss to $27.4 million from $33.2 million a year ago. Adjusted EBITDA loss improved to $18.0 million from $26.3 million in Q3 2025. The trend is better. The company is still investing heavily.
Then there's the balance sheet. Cash and equivalents exploded to $4.45 billion from $829 million at year-end 2025, driven by $3.9 billion in ATM equity proceeds. That stockpile fully covers the pending Iridium Communications acquisition, which has cleared shareholder and lender approvals. Rocket Lab also recorded a $27.3 million loss on debt extinguishment in Q3 from paying off convertible notes. With Iridium funded and the balance sheet fortified, financing risk has exited the near-term thesis.
Q4 guidance points to revenue of $270 million to $290 million. At the $280 million midpoint, another sequential record. Adjusted EBITDA loss is expected at $14 million to $20 million, continuing the narrowing trend. Stock-based compensation is guided at $17 million to $19 million, roughly matching Q3's $18.3 million.
The 52% sequential backlog growth is the number that matters. It shows large customers buying into the end-to-end strategy with multi-launch, multi-spacecraft commitments. Once closed, Iridium adds a mature, cash-generating business. The open question is margins: Neutron costs stay elevated through first flight, and the product revenue mix could keep GAAP gross margins below 35% for several quarters. But with $4.5 billion in cash and $3.6 billion in backlog, Rocket Lab has the runway to execute.